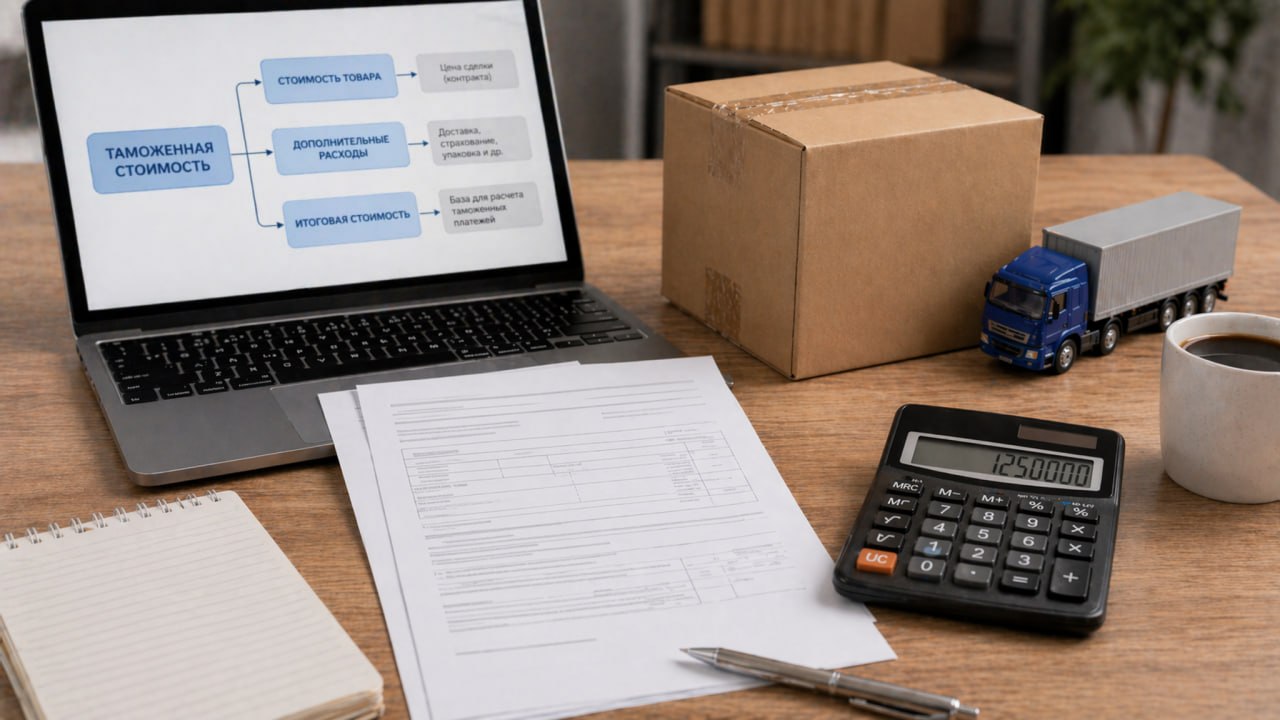
One of the key areas of customs control is the control of the customs value of goods, since it is the customs value that is the basis for calculating customs duties, taxes and other mandatory payments.
At the same time, the verification of documents and information on the customs value is not carried out for every declaration of goods. Control is carried out using a risk management system that allows you to identify supplies that require additional verification, and at the same time minimize the administrative burden on bona fide participants in foreign economic activity.
Verification of documents and information on the customs value is appointed if there are signs of a possible false declaration of the customs value. In particular, the basis for conducting an inspection may be identified discrepancies between the submitted documents, a significant deviation of the declared value from the value of identical or similar goods, the absence of documentary evidence of individual components of the customs value, as well as other circumstances indicating possible non-compliance with the requirements of customs legislation.
Special attention is paid to the completeness of the formation of the customs value structure. The customs authorities verify the correctness of the inclusion in the customs value of transportation costs, insurance, royalties and other charges, which, in accordance with the legislation, are subject to accounting when determining the customs value of goods.
At the same time, the customs legislation of the Eurasian Economic Union provides for mechanisms to simplify customs administration.
Thus, verification of documents and information on the customs value may not be carried out with respect to identical goods imported under the same foreign trade agreement, if earlier for a similar delivery the customs authority had already confirmed the authenticity of the declared customs value using the transaction value method for imported goods (method 1).
In order to apply this mechanism, the conditions established by law must be observed at the same time. In particular, the goods must be imported under the same foreign trade agreement as the previously issued delivery, and the declared customs value must be determined by the same method — according to the transaction value of the imported goods. In addition, the essential terms of the transaction that affect the formation of the customs value must remain unchanged, including the price of the goods, the commercial terms of sale, the terms of delivery and the settlement procedure between the parties.
It is also a prerequisite that there are no new circumstances that could affect the value of the customs value or raise doubts about the accuracy of the information provided. The goods declaration must contain information about a previously completed delivery, for which the customs authority has already confirmed the customs value. This allows the customs authority to compare the data of the current delivery with previously verified information and decide not to apply additional verification measures.
It should be borne in mind that even if these conditions are met, the customs authority has the right to conduct an inspection if, within the framework of the risk management system, signs of a possible violation of customs legislation are identified or information appears indicating the unreliability of the declared data. Thus, the exemption from verification is not unconditional and is applied only in the absence of risk factors.
This approach makes it possible to focus control measures on shipments that show signs of risk, while simultaneously speeding up customs clearance for bona fide participants in foreign economic activity.
Thus, the application of a risk management system ensures a balance between effective customs control and the creation of favorable conditions for conducting foreign economic activity, as well as contributes to increasing transparency and predictability of customs administration.